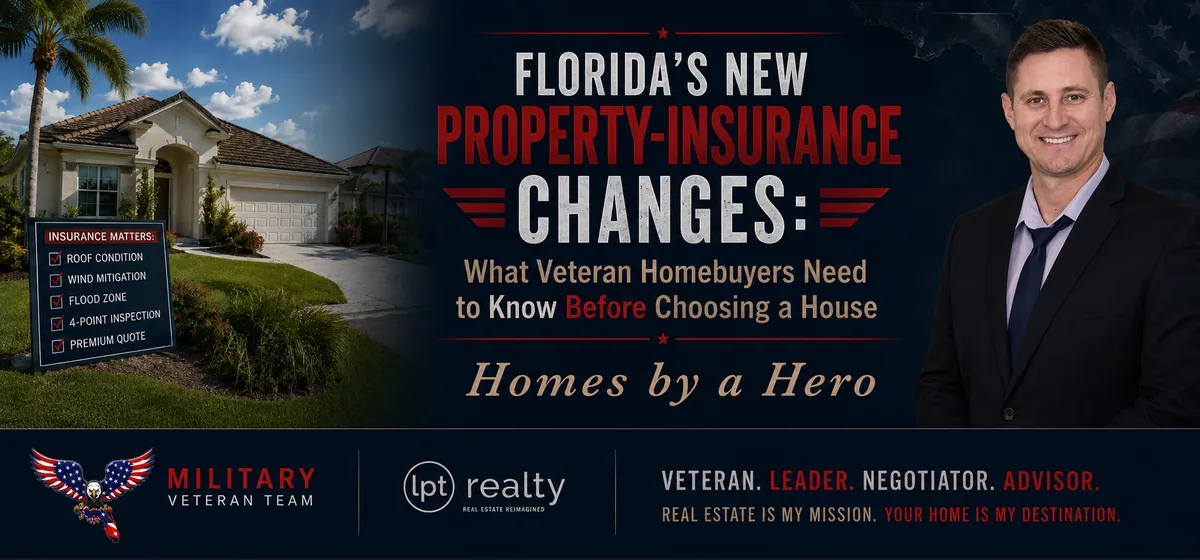
Florida’s New Property-Insurance Changes: What Veteran Homebuyers Need to Know Before Choosing a House
Buying a home in Florida has always required more than comparing price, bedrooms, and commute time.
Insurance can change the entire equation.
For military families and veterans relocating to Florida, that matters even more because PCS timelines can create pressure to make decisions quickly. A house may look affordable based on the mortgage payment alone, but the insurance cost, roof condition, hurricane protection, and flood exposure can make one property dramatically more expensive to own than another.
Florida made several property-insurance changes in 2026 that buyers should understand before choosing a home.
The My Safe Florida Home Program Expanded
Florida updated the My Safe Florida Home program in June 2026.
One important change broadened eligibility for certain attached properties. The program now uses an “attached property” definition that can include qualifying homes sharing a wall with another dwelling, provided they meet the program’s requirements and are no more than three stories.
The state also clarified that eligible roof improvements can include replacing the roof covering.
That matters because roof condition is one of the biggest insurance considerations Florida buyers encounter.
For veterans buying an older Florida property, potential eligibility for hurricane-mitigation assistance could become part of the long-term ownership strategy.
Roof Age Still Matters, But It Is Not the Whole Story
Florida law provides important protections involving older roofs.
An insurer cannot refuse to issue or renew a homeowners policy solely because a roof is less than 15 years old.
For roofs 15 years or older, the homeowner must generally be allowed to obtain an inspection before the insurer requires replacement based solely on age. If that inspection shows the roof has at least five years of useful life remaining, the insurer cannot reject coverage based only on roof age.
That does not mean every older roof will be inexpensive to insure.
It means buyers should investigate the actual condition rather than assuming a certain birthday automatically makes a house uninsurable.
Home Hardening Got Another Boost
Florida also extended its Home Hardening Sales Tax Exemption through June 30, 2029 for qualifying products.
Eligible items can include certain impact-resistant windows, doors, and garage doors designed to withstand wind and debris. Qualifying homeowners may also be eligible for a refund of up to $500 under the program’s rules.
For military and veteran homeowners, this creates another reason to look closely at hurricane protection already installed on a property.
A home with impact windows, appropriate shutters, and modern wind-resistant features may cost more upfront but potentially provide insurance and storm-resilience benefits over time.
Insurance Should Be Part of the Home Search
This is the bigger lesson.
In Florida, insurance should not be something you investigate after falling in love with the house.
Ask about it early.
Before making an offer—or certainly before your inspection period expires—consider obtaining realistic insurance estimates.
The insurer may evaluate:
Roof age and construction
Building materials
Location
Property size
Wind-mitigation features
Prior claims
Previous insurance history
Florida’s Department of Financial Services specifically notes that homeowners insurers use these types of property characteristics during underwriting.
A Home Inspection and an Insurance Inspection Are Not the Same Thing
Military buyers should understand another important distinction.
A standard home inspector looks at the general condition of the property.
An insurance company may require additional reports.
For an older home, that could include a 4-point inspection, which typically examines the roof, plumbing, electrical system, and heating/air conditioning.
A wind-mitigation inspection can separately document hurricane-resistant features that may qualify the homeowner for premium credits.
These reports can have a direct effect on your insurance options.
Do Not Judge Affordability by Mortgage Alone
Imagine two Florida homes both priced at $425,000.
The mortgage calculation may look almost identical.
But suppose one has:
A newer roof.
Impact-rated windows.
Better wind mitigation.
Lower flood exposure.
Lower insurance premiums.
The other property could cost hundreds of dollars more each month to own even though the sale price is the same.
That is why the “cheaper” house is not always actually cheaper.
Ask for Insurance Information Before You Commit
When I work with military families buying in Tampa Bay, I encourage them to investigate insurance early enough that it can influence the decision.
Ask:
How old is the roof?
Is there a recent wind-mitigation report?
Was a 4-point inspection completed?
Has the home had major insurance claims?
Is flood insurance likely?
What would an insurance agent realistically charge for this specific property?
Those answers belong next to the mortgage payment when comparing homes.
The Bottom Line
Florida’s 2026 insurance changes give homeowners additional options around hurricane mitigation, roof improvements, and home hardening.
But the biggest advantage still comes from being informed before buying.
For military families and veterans, the best home is not simply the one that qualifies for the VA loan.
It is the one that remains affordable after mortgage, taxes, insurance, maintenance, and Florida’s unique storm-related ownership costs are included.
If you are considering a home in Tampa Bay, I would be glad to help you compare the real ownership costs before you make the commitment.
Matthew Halliday
Navy Veteran | Realtor
Military Veteran Team | LPT Realty
Homes by a Hero